7 min read
How the Appraisal Clause Works in a Utah Homeowners Policy
Who can demand appraisal, how appraisers and umpires are chosen, and what the award does and doesn’t decide.
Independent claim appraisal · All 29 Utah counties
Your insurer agreed the damage is covered, then sent a number that won’t rebuild it. Utah Insurance Appraiser prepares an independent, line-by-line valuation and carries it through the appraisal process written into your policy.
We measure first, then price
Why owners call
Most underpaid claims aren’t denials. They’re estimates that stop short: two roof slopes instead of four, a basement floor patched when the planks are discontinued, drywall replaced with no allowance for the knockdown texture. Utah Insurance Appraiser exists for the space between “covered” and “paid in full.”
Services
Twelve services, one goal: a valuation of your loss that stands up. Bring Utah Insurance Appraiser in for a quick estimate review or once appraisal has been demanded.
 01
Once appraisal is demanded, we act as the appraiser you name and carry your valuation to the panel.
Learn more 02
Independent valuation for single-family homes, cabins and townhomes when the carrier’s estimate falls short.
Learn more 03
Appraisal for retail, office, industrial, multifamily, church and HOA properties with large or complex losses.
Learn more04Hail and roof claims valued with real measurements, slope-by-slope documentation and complete line items.
Learn more 05
Canyon windstorms, microbursts and the occasional tornado: valued with the full scope of roof, siding, fence and tree damage.
Learn more 06
Winter losses: roof collapse from snow load, ice-dam leaks and burst pipes in homes, cabins and commercial buildings.
Learn more 07
Sudden water losses from supply lines, appliances, water heaters and roof leaks, priced with complete mitigation and rebuild.
Learn more 08
Structure fires and smoke losses valued with full cleaning, deodorization, rebuild and contents scope.
Learn more 09
Wildland-urban interface losses: total losses, partial burns, ash, smoke infiltration and landscape and outbuilding damage.
Learn more 10
For owners with earthquake endorsements: cracking, masonry, foundation and chimney damage valued against a high deductible.
Learn more 11
A line-by-line audit of the carrier’s estimate so you know exactly what was missed before deciding on appraisal.
Learn more 12
Neutral umpire work for appraisal panels that can’t agree, with a transparent, well-documented decision process.
Learn moreFive claim climates
Hail in Orem, canyon wind in Layton, roof-crushing snow in Park City, sub-zero cold in Logan and monsoon storms in St. George. A Utah Insurance Appraiser has to know how each region’s weather shows up in a building and in an estimate.
Canyon windstorms, summer hail, ice dams and the occasional tornado, layered over century-old brick homes, mid-century ranches and high-rise condos.
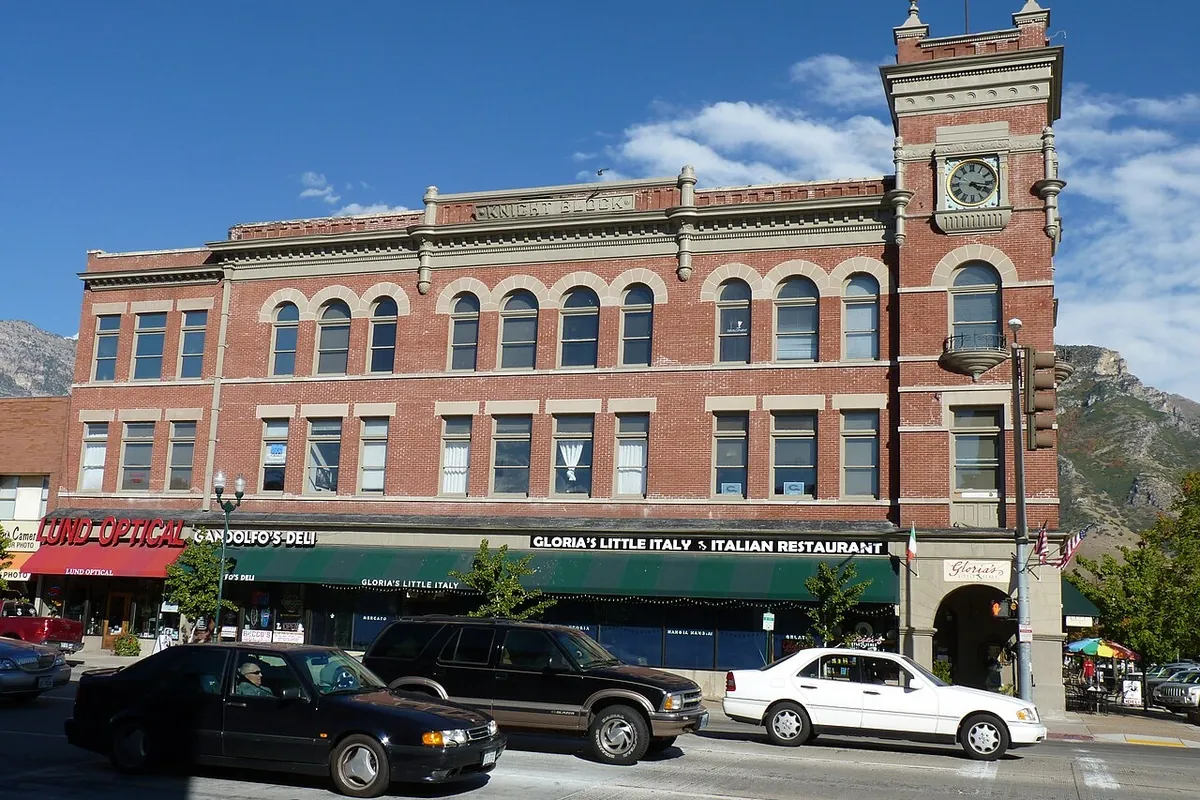
Fast-growing subdivisions, student rentals and foothill homes exposed to hail, wildfire smoke and winter water losses.
The heaviest snow loads in the state, frozen pipes in empty second homes and high-end finishes that valley pricing misses.
Long, cold winters and agricultural outbuildings make frozen pipes, snow-load collapses and barn claims a regular pattern.
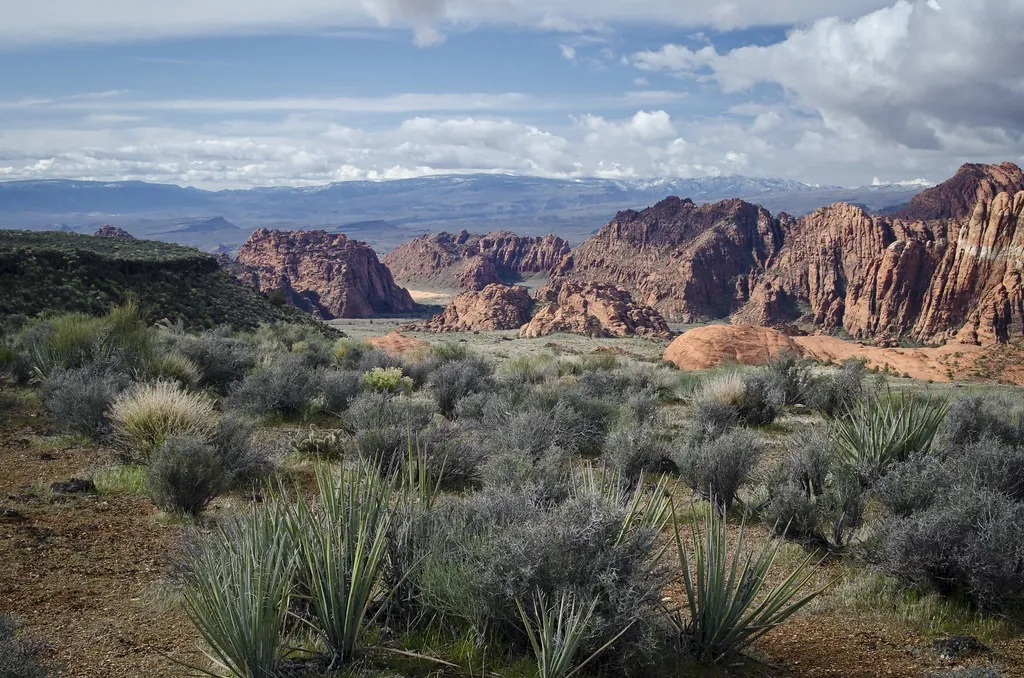
Monsoon wind, flash floods, stucco and tile roofs, plus wildfire country around Brian Head and Cedar Mountain.
Quick gap check
Enter the two numbers you already have. A large difference is worth a conversation with a Utah Insurance Appraiser. A small one may close faster with a documented supplement request.
The full claim gap and fee estimator subtracts appraiser and umpire fees so you see a realistic net.
All seven calculatorsThe process
The appraisal clause turns an open-ended argument into a defined process. Here is the route Utah Insurance Appraiser takes once an amount dispute is confirmed.
Gather the carrier’s full estimate, your own estimate, photos and correspondence. Submit a written supplement request explaining what’s missing. Many disputes close here.
If the gap remains, either party can demand appraisal in writing under the policy’s appraisal condition, naming or promising to name an appraiser.
You and the insurer each select a competent, impartial appraiser, usually within a set number of days stated in the policy.
The two appraisers agree on a neutral umpire. If they can’t, many policies allow a court in the county where the property sits to appoint one.
The appraisers inspect, compare measurements and pricing, and agree on as many items as they can. Many files end with an agreed award.
Remaining items go to the umpire, who reviews both positions and the evidence, then joins one appraiser on each disputed item.
Utah storm record
Utah’s biggest property losses rarely come from one kind of storm. Floods, tornadoes, windstorms, wildfire, earthquakes and record snow have all tested local policies. Utah Insurance Appraiser keeps that history in mind when reading damage and policy language.
A record snowpack melted fast, turning State Street in Salt Lake City into a sandbagged channel and flooding communities statewide.
On August 11, a tornado crossed downtown, the Avenues and Capitol Hill, damaging hundreds of buildings.
In January, flooding on the Santa Clara and Virgin rivers destroyed and damaged homes in Washington County.
On December 1, downslope gusts over 100 mph tore through Centerville, Farmington and neighboring towns.
A summer wildfire in Iron and Garfield counties burned for weeks and destroyed homes and cabins.
A magnitude 5.7 quake in March, then a September downslope windstorm that toppled thousands of trees.
Months of heavy snow led to roof and carport failures, ice dams and spring flood worries across northern Utah.
Free and private
Check the numbers before you call anyone. Each calculator runs in your browser, and nothing you type is stored or sent.
 ΔEstimator
Size the dispute, test where an award could land and subtract appraiser and umpire fees to see your net.
 ACVCalculator
List damaged items by age and life expectancy to see the first check, the depreciation held back and the total.
▲EstimatorTurn a footprint into real roof squares with pitch and waste, then compare against the carrier’s roof section.
%CalculatorConvert an earthquake, wind or hail percentage deductible into dollars and see what a claim would actually pay.
◷PlannerMap notice, mitigation, proof-of-loss, holdback and suit dates from your date of loss, then export them to a calendar.
✓ChecklistTwelve yes/no questions that score your claim file and build a to-do list before you demand appraisal.
 ❄Estimator
Convert snow depth, snow type and ice into pounds per square foot and total roof weight for a winter claim.
Right tool, right time
Appraisal solves one problem well. A good Utah Insurance Appraiser will tell you when your claim needs something else.
FAQ
Plain answers about the process, the cost and when appraisal is the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your selected appraiser, we inspect, build an independent line-item estimate, work with the insurer’s appraiser and, if needed, present unresolved items to a neutral umpire.
No. A public adjuster presents and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When coverage has been accepted, you have the insurer’s estimate, and the gap between it and a contractor’s number is meaningful. As a rough guide, more than about 10% or several thousand dollars.
On the amount of loss, generally yes, once any two of the three panel members sign. It doesn’t decide coverage.
Each side pays its own appraiser and usually half of the umpire. We put our fee in writing before any work starts. The first conversation is free.
Yes. We cover all 29 Utah counties, including Cache Valley, the mountain resort areas and southern Utah.
Articles
Practical articles from Utah Insurance Appraiser on policy wording, winter claims and documentation.
Who can demand appraisal, how appraisers and umpires are chosen, and what the award does and doesn’t decide.
How to document snow-load and ice-dam damage, what estimates commonly miss and where coverage gets tricky.
A step-by-step list for the days after a downslope windstorm, from tree removal to fence and siding scope.
Before you sign off
A short, free review can keep you from accepting a settlement that won’t cover the repair.
Start here
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing.